
PFCS INSIGHTS · SEPTEMBER 25, 2026
Intercreditor Agreements in Commercial Lending: A Borrower’s Guide
A financing plan can involve more than one creditor with rights in the same borrower, collateral, cash flow, or guarantor. A senior lender, equipment financier, seller noteholder, mezzanine provider, asset-based lender, real estate lender, or affiliate may each expect protections that cannot be understood from a lien label alone. An intercreditor agreement can allocate priority, payments, control, remedies, releases, and proceeds among those creditors, and unresolved terms can delay closing or restrict future financing. Borrowers can reduce surprises by building a complete debt-and-collateral map, identifying conflicts early, and modeling how the documents work in ordinary operations as well as after default. This guide is educational, not legal, tax, accounting, bankruptcy, investment, or financial advice; qualified counsel and the affected creditors determine the transaction-specific structure and legal effect.
01
Understand why creditors need a common rulebook
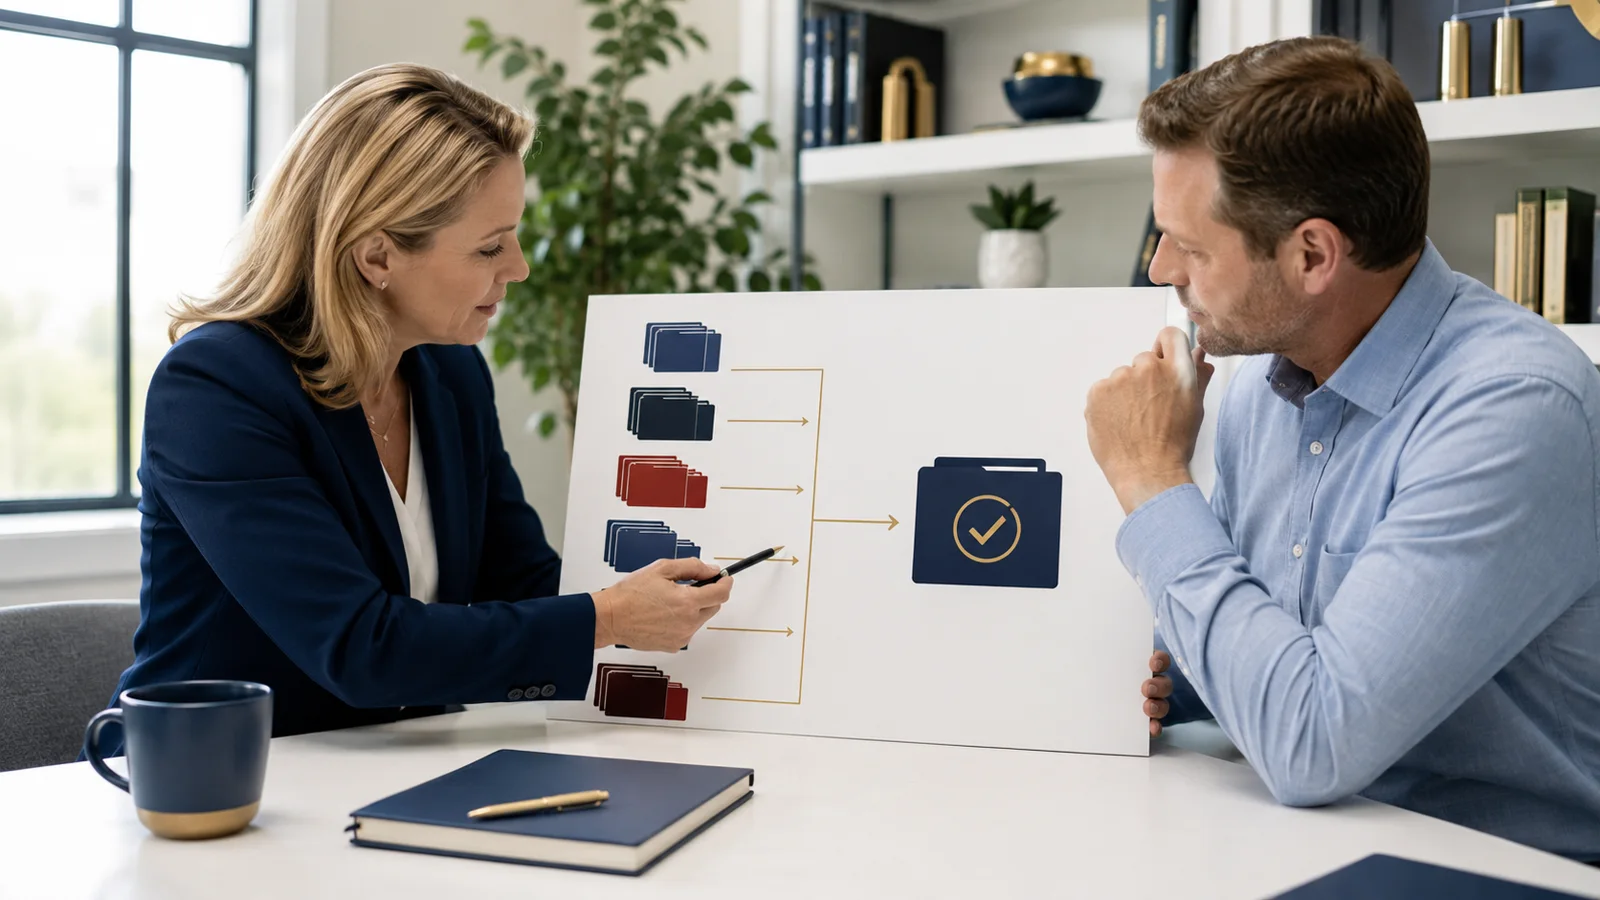
When two or more creditors have claims against the same borrower, guarantor, collateral, or proceeds, separate loan documents may create competing rights. An intercreditor agreement can establish how the creditors rank and interact without changing every obligation the borrower owes. It may address lien priority, debt payments, notices, remedies, collateral releases, insurance or condemnation proceeds, refinancing, amendments, and bankruptcy-related rights. The title is not enough: a subordination agreement, lien-priority agreement, split-collateral arrangement, unitranche agreement, or recognition agreement can allocate risk differently.
02
Build a complete creditor and debt inventory
List every bank loan, line of credit, mortgage, equipment lease or financing, seller note, shareholder loan, earnout, factoring arrangement, merchant obligation, tax lien, judgment, guarantee, letter of credit, and affiliate advance. For each item, record the legal obligor, creditor, committed amount, current balance, maturity, payment schedule, security, guarantors, covenants, default status, prepayment terms, and filing or control documents. Reconcile the schedule to the general ledger, tax returns, bank statements, UCC searches, title reports, credit reports, and payoff letters. An omitted obligation can invalidate the working priority map.
- Requested amount and use of proceeds
- Historical and current financial statements
- Complete debt and ownership schedules
- Collateral and transaction documentation
- 01Map every creditor and claim
- 02Define control and cash flow
- 03Protect operations and future financing
03
Map collateral by asset rather than using broad labels
Create an asset-level matrix for accounts, inventory, equipment, vehicles, deposit accounts, securities accounts, intellectual property, real estate, leases, rents, insurance, proceeds, equity interests, and after-acquired property. Identify ownership, location, value support, existing liens, perfection method, excluded assets, and which creditor expects first or junior priority. A creditor may be senior on one asset class and junior on another. Qualified counsel should determine attachment, perfection, and priority under applicable law rather than relying only on a financing-statement search.
04
Separate lien subordination from payment subordination
Lien subordination generally addresses priority in collateral and its proceeds. Payment subordination can restrict when a junior creditor may receive principal, interest, fees, or other transfers, even while the business is operating. Read the permitted-payment basket, blockage triggers, blockage duration, cure, turnover obligations, accrual treatment, and whether payments resume automatically. Model scheduled debt service and cash flow under both normal and blocked-payment periods so the borrower understands liquidity and accounting consequences.
05
Define control and enforcement standstills precisely
A senior creditor may control collateral decisions and require a junior creditor to wait before exercising remedies. Confirm which defaults start a standstill, how notice is delivered, how long the period lasts, whether it can restart, and what actions remain permitted. The agreement may distinguish acceleration, suit, foreclosure, collection, setoff, account control, bankruptcy filings, and protective advances. Align those provisions with each loan agreement so the borrower is not subject to incompatible deadlines, notices, or remedy triggers.
06
Trace every category of proceeds and recovery
Specify how ordinary-course collections, asset-sale proceeds, insurance recoveries, condemnation awards, warranty claims, tax refunds, escrow releases, and enforcement proceeds move through the structure. Confirm application order, expenses, protective advances, interest, principal, reserves, surplus, and any shared or excluded proceeds. Compare the waterfall with lockbox, deposit-account control, cash-management, mortgage, security, and insurance documents. A priority concept that cannot be executed through the actual accounts and payment systems is a closing and operating risk.
07
Make releases and routine transactions workable
Borrowers may need to sell obsolete equipment, replace financed assets, collect receivables, grant customer credits, renew leases, complete acquisitions, or dispose of property in the ordinary course. The intercreditor agreement should be read alongside each lender's release and consent provisions to determine who can authorize a release and whether junior liens terminate automatically after an approved senior disposition. Track required notices, payoff amounts, release documents, UCC amendments, title actions, and timing so an asset sale or refinance is not trapped by an unanticipated consent.
08
Protect amendments, additional debt, and refinancing capacity
Intercreditor terms may limit changes to rates, maturity, principal, covenants, collateral, guarantees, or enforcement rights and may define how much senior or junior debt can be added. Review debt caps, permitted refinancings, successor-lender requirements, accession documents, purchase options, and assignments. Test future scenarios such as a line increase, equipment purchase, real estate refinance, acquisition, ownership change, or lender replacement. A structure that closes today's transaction but blocks a foreseeable capital need may be too rigid.
09
Coordinate negotiation through one closing matrix
Identify each party's counsel, authorized signer, form requirements, approval process, fees, open comments, payoff conditions, filings, control agreements, mortgages, landlord or bailee documents, and required deliveries. Keep one issues list distinguishing commercial decisions from legal drafting. Ask the proposed lenders to surface nonnegotiable priority and remedy requirements early. Do not assume that agreement between the borrower and one lender binds another creditor or that an email summary replaces signed documents and required filings.
010
Monitor the arrangement after funding
Retain the executed agreement with a current debt schedule, collateral map, notices, and related loan documents. Monitor payments, covenant compliance, new debt, asset sales, account changes, collateral moves, lien filings, ownership changes, amendments, defaults, and notices. Obtain required consents before making a junior payment, granting another lien, refinancing debt, or disposing of material collateral. PFCS can help organize the financing package and coordinate information with third-party capital sources, but each creditor and qualified counsel determine priority, enforceability, required consents, approval, and final terms.
05
Financial Comparison and Underwriting View
| Review area | What a lender may evaluate | Practical borrower action |
|---|---|---|
| Cash flow | Historical and projected ability to service debt | Use reconciled statements and explain adjustments |
| Leverage | Debt relative to value or capitalization | Test proceeds under conservative values |
| Liquidity | Capacity to absorb delays and volatility | Document verified post-closing liquidity |
| Execution | Experience, documents, and transaction readiness | Resolve missing reports before submission |
Related PFCS Guidance
Explore PFCS guidance for commercial real estate financing, review business growth financing options, or learn how SBA loan coordination may fit an eligible transaction.
PFCS provides independent, borrower-first transaction analysis, underwriting coordination, and customized capital solutions sourced from third-party lenders.
Contact PFCS about your financing need →06
Frequently Asked Questions
Does PFCS provide loans directly?+
No. PFCS is an independent commercial finance consulting and brokerage firm that coordinates requests with third-party lenders.
Does submitting information guarantee financing?+
No. Approval, pricing, structure, timing, and funding remain subject to lender underwriting, eligibility, documentation, and final approval.
What documents should a borrower prepare first?+
Most reviews begin with a financing summary, recent financial statements, tax returns, debt schedules, ownership information, and transaction-specific documents.
Can lender requirements change?+
Yes. Requirements, programs, pricing, and credit criteria can change and may vary by lender and transaction.
Educational information only; not financial, legal, tax, or investment advice. PFCS is not a bank or direct lender. Financing is subject to third-party lender underwriting, eligibility, approval, documentation, and applicable law.